
Semiconductor Plant Construction Market Forecast To Hit $64.8 Billion By 2030 Amid Strong Industry Growth
Semiconductor Plant Construction Market
Semiconductor Plant Construction
Semiconductor Plant Construction Market Size
The Business Research Company’s Semiconductor Plant Construction Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON , UNITED KINGDOM, October 28, 2026 /EINPresswire.com/ -- The semiconductor plant construction sector is undergoing a significant transformation, driven by technological advancements and strategic partnerships. With AI-enabled automation becoming increasingly integral, the industry is setting new standards in efficiency and precision. This overview dives into the current market dynamics, influential players, growth factors, and emerging trends shaping the future of semiconductor fabrication infrastructure.
Semiconductor Plant Construction Market Valuation and Growth Trajectory
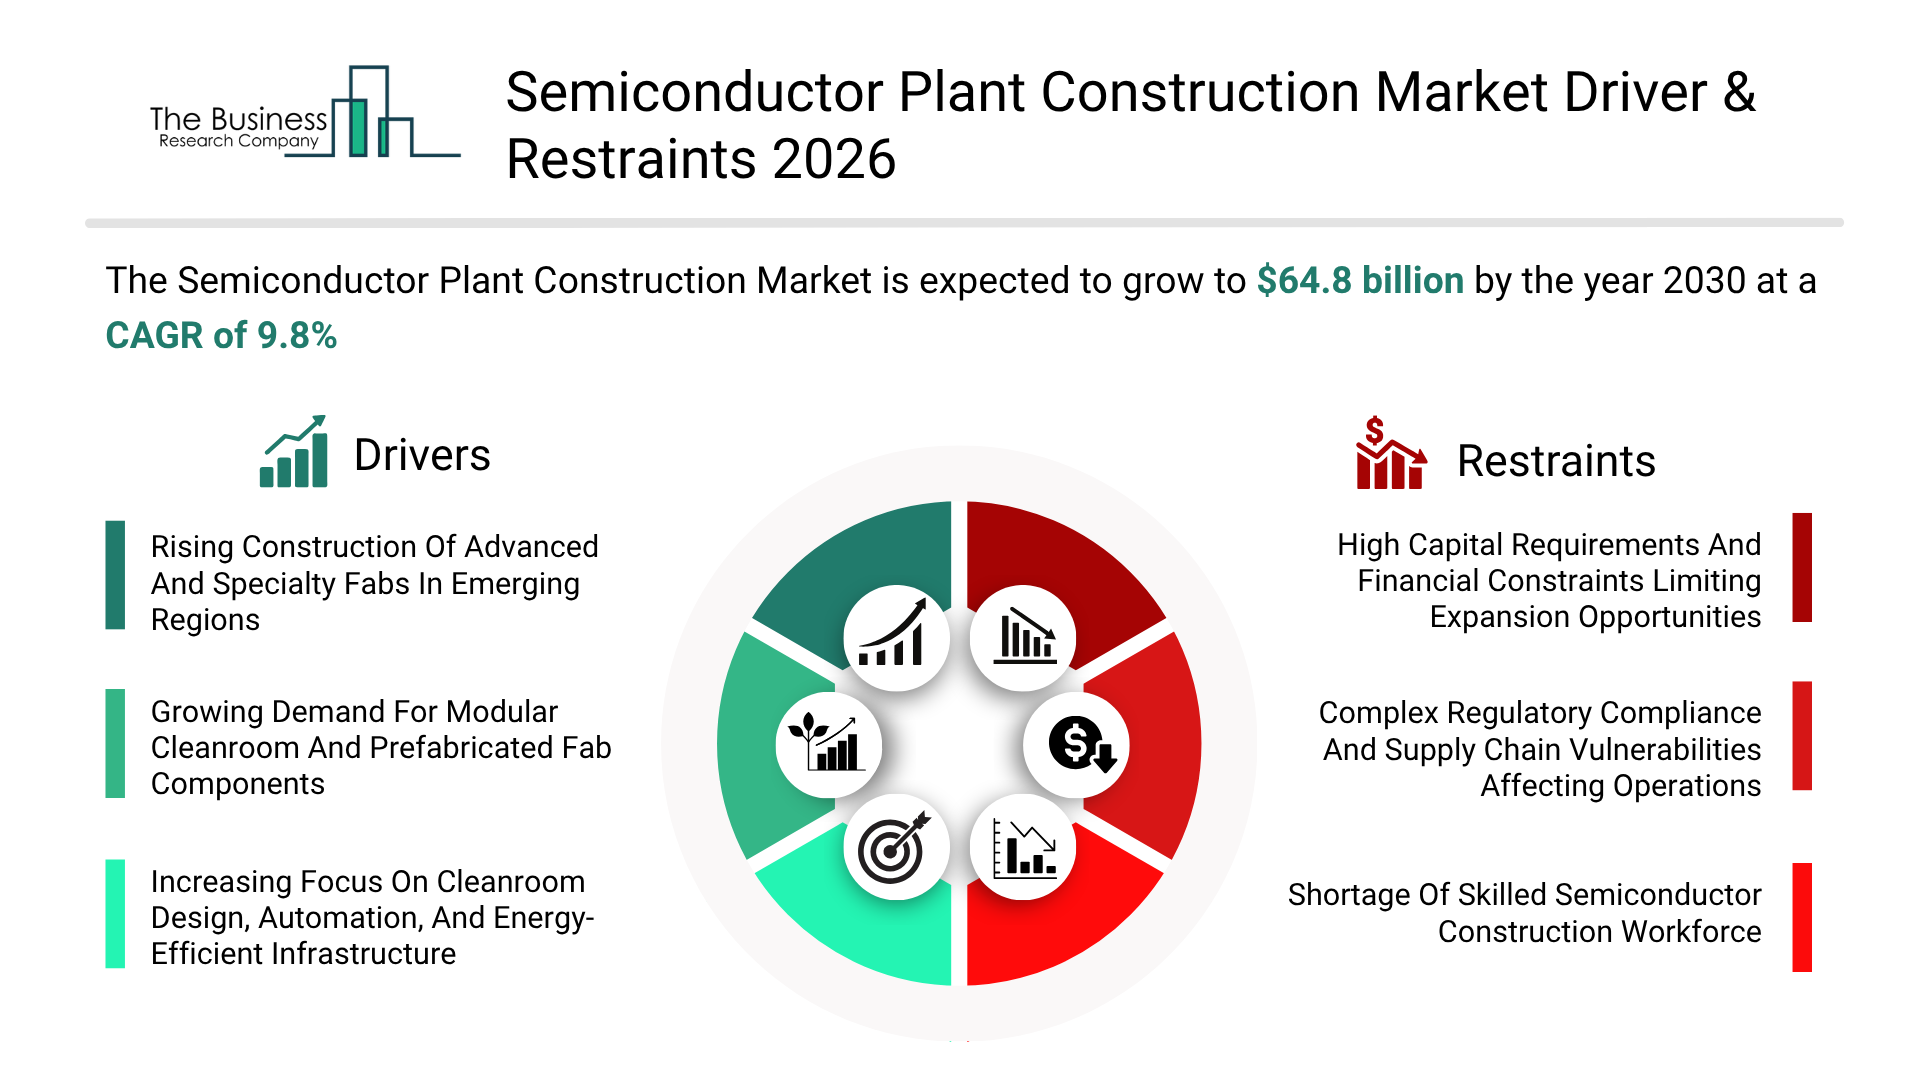
The semiconductor plant construction market is forecasted to surpass $65 billion by 2030. This segment forms a notable part of the larger Commercial Buildings market, which is expected to reach approximately $2,333 billion by the same year, with semiconductor plant construction contributing around 3%. Within the construction industry overall, projected to hit $21,691 billion by 2030, this segment will account for nearly 0.3%. Analysts anticipate a strong compound annual growth rate (CAGR) of 10% through the end of the decade, reflecting robust demand for specialized semiconductor manufacturing facilities.
Request A Free Sample Of The Semiconductor Plant Construction Market Report
https://thebusinessresearchcompany.com/sample_request?id=83694543&type=smp&name=Semiconductor%20Plant%20Construction%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Regional Spending Highlights in Semiconductor Plant Construction
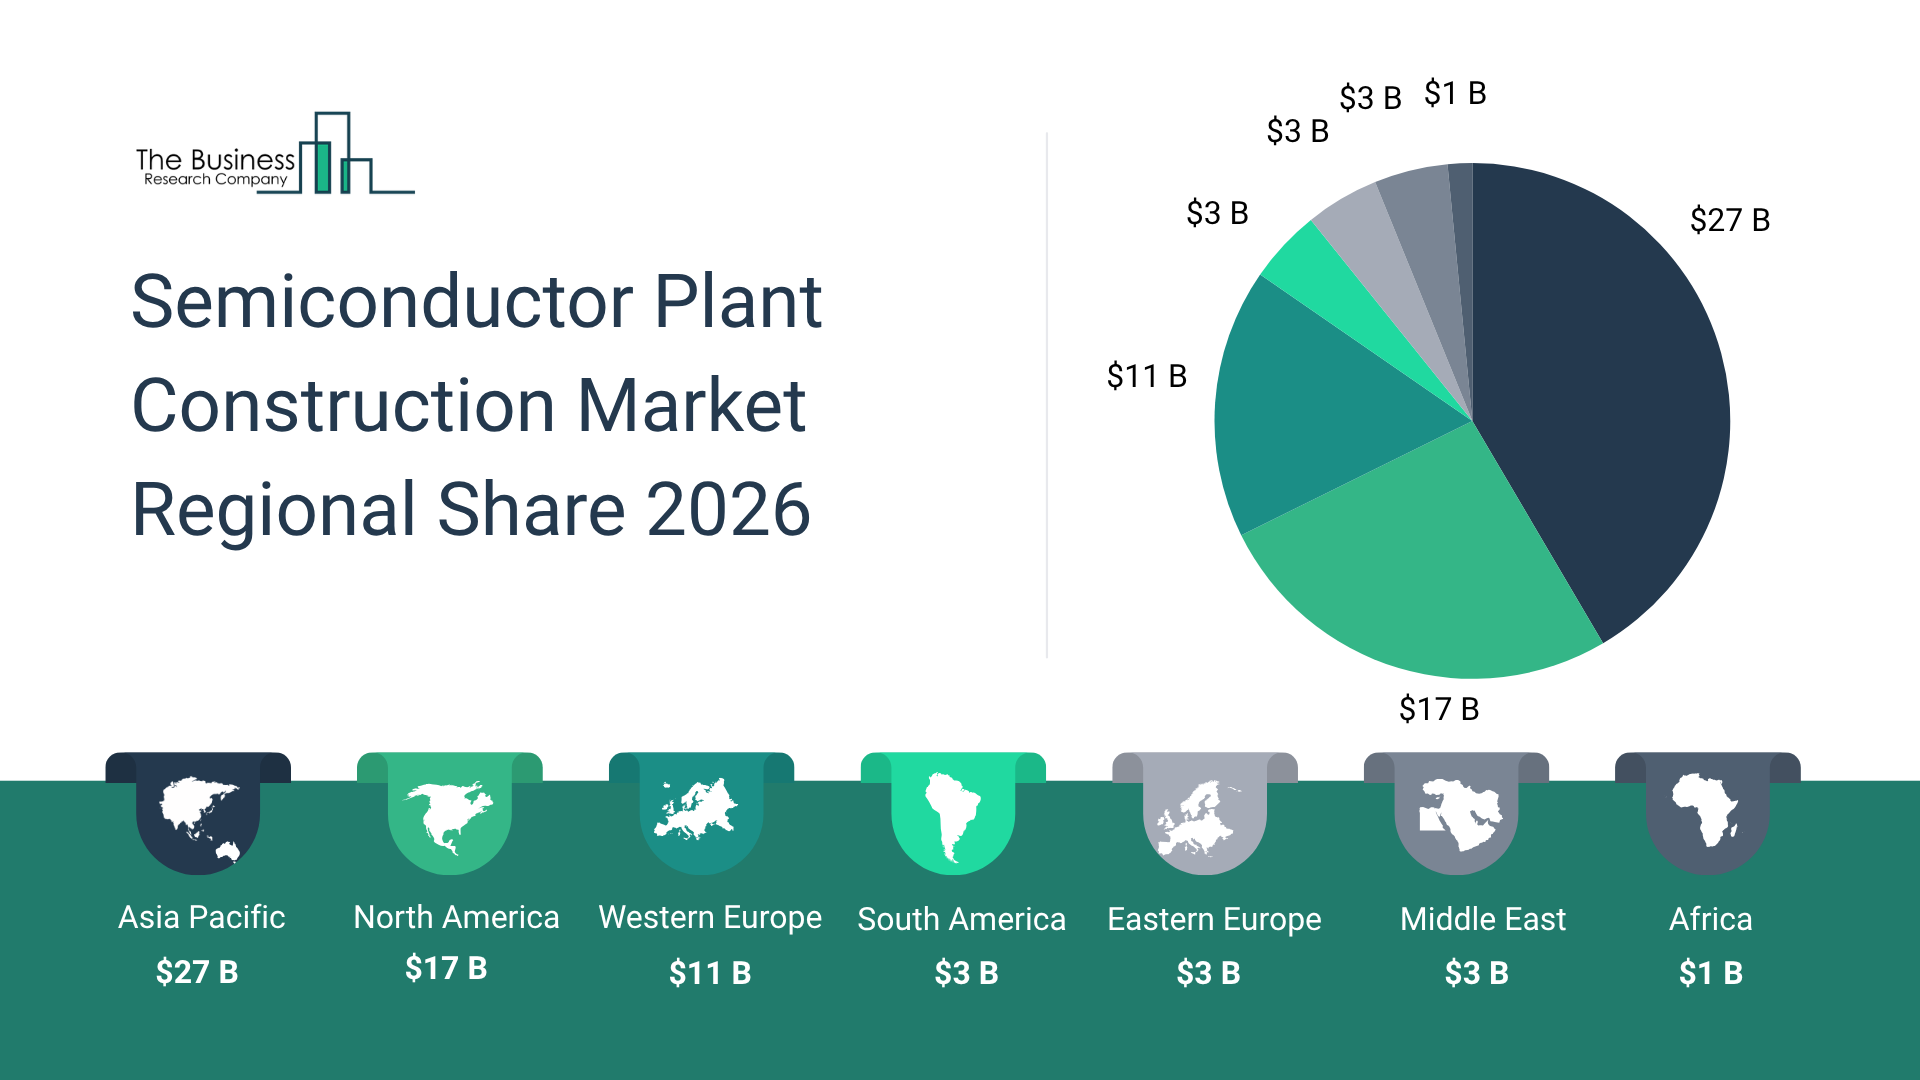
The Asia-Pacific region is set to lead the semiconductor plant construction market by 2030, with a valuation of $27 billion, rising from $16 billion in 2025 at an 11% CAGR. This rapid expansion mirrors aggressive investments in chip manufacturing capacity, including advanced fabs and wafer plants, supported by extensive government incentives to promote domestic production and localized supply chains. Major projects in Taiwan, South Korea, China, Japan, India, and Southeast Asia underscore this growth trend, driven largely by demand from consumer electronics and automotive sectors.
The United States will hold the position as the largest single country market within this sector, projected to reach $15 billion in 2030, up from $10 billion in 2025 at a 10% CAGR. Growth here is primarily fueled by the CHIPS and Science Act, which encourages domestic fab and packaging plant development. The country’s expansion of foundry and integrated device manufacturing capacity, alongside enhanced collaboration between semiconductor firms and engineering contractors, is also propelling the sector forward. The ongoing buildup of advanced manufacturing ecosystems and industrial infrastructures further supports this momentum.
Access The Detailed Semiconductor Plant Construction Market Report Here
https://thebusinessresearchcompany.com/report/semiconductor-plant-construction-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Distribution of Market Share by Construction Type
Within semiconductor plant construction, new building projects dominate the market, comprising 58% of the total value or about $38 billion by 2030. This segment benefits from the rise of greenfield fabs, investments in next-generation cleanrooms, and the growing need for high-capacity plants tailored to advanced semiconductor processes. Facilities dedicated to specialty and compound semiconductors, energy-efficient designs, integrated utility systems, and precision manufacturing environments all contribute to this substantial share.
Additional Market Segments Based on Facility and Equipment
The market breaks down further into several categories by facility type, including wafer fabrication facilities, assembly and test centers, and research and development hubs. Equipment segmentation includes lithography, deposition, etching, chemical mechanical planarization, cleaning, and other specialized tools. Infrastructure is also classified into electrical systems, mechanical systems, networking, safety and security arrangements, and other critical infrastructure components needed for modern semiconductor plants.
Three Core Factors Driving Market Expansion
One major growth driver is the surge in construction of advanced and specialty fabs, especially in emerging economies. Governments and private investors are heavily funding domestic chip production to reduce reliance on imports. Each new fab requires comprehensive site development, cleanroom construction, and sophisticated utility systems. Supportive tax incentives and infrastructure improvements in these regions encourage geographic diversification, boosting demand for expert engineering and construction services. This driver is expected to add around 2.0% annual growth to the market.
Another important factor is the increasing preference for modular cleanroom designs and prefabricated fab components. These solutions enable quicker installations, cost savings, and easier future expansions. Prefabricated parts reduce onsite labor and complexity, while the rapid pace of technological change encourages adaptable infrastructure. This trend is projected to contribute roughly 1.8% annual growth.
A third key influence is the heightened focus on cleanroom design, automation, and energy-efficient infrastructure. Semiconductor manufacturing demands controlled environments, so advanced cleanrooms, automated materials handling, and smart facility management are becoming standard. Energy-saving systems not only reduce operational expenses but also align with sustainability goals. This complexity and sophistication increase project value and create opportunities for specialist contractors. This factor is estimated to add about 1.3% annual growth to the sector.
The Role of AI Automation in Revolutionizing Semiconductor Plant Construction
AI-driven automation is reshaping the way semiconductor plants are built and run, enhancing operational efficiency, cutting costs, and improving chip fabrication accuracy. A prime example is the partnership formed in December 2024 between Tata Electronics and Powerchip Semiconductor Manufacturing Corporation to develop India's first AI-enabled semiconductor fab in Dholera, Gujarat. These facilities leverage real-time process optimization and predictive maintenance technologies, minimizing downtime while enhancing product quality throughout manufacturing operations.
Exyte as the Leading Force in Semiconductor Plant Construction
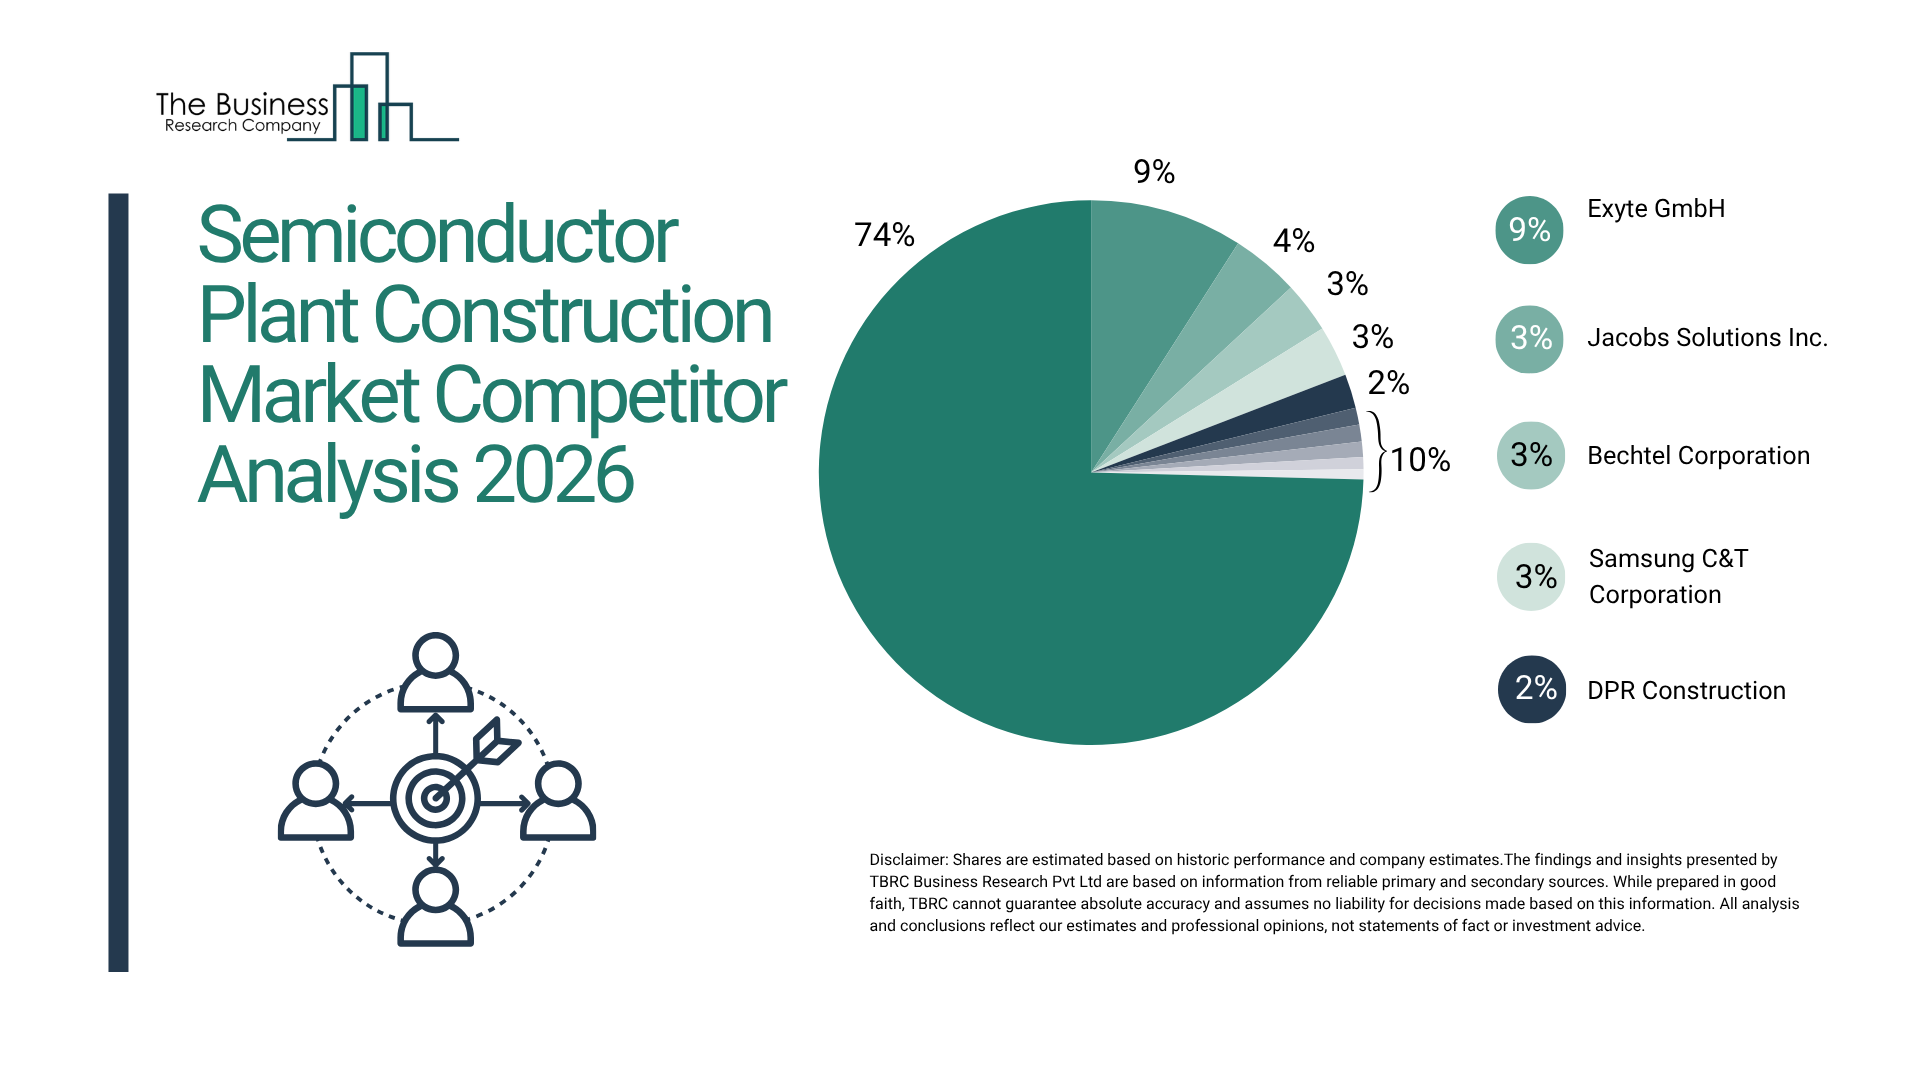
Exyte GmbH currently holds the largest market share in this industry, commanding 9% of global sales in 2025. Its advanced technology facilities division directly supports semiconductor plant construction by offering specialized engineering, design, construction, and project management services for chip fabs, cleanrooms, and high-tech manufacturing sites.
Key Players Active in the Semiconductor Plant Construction Market
Besides Exyte GmbH, prominent companies include Jacobs Solutions Inc., Bechtel Corporation, Samsung C&T Corporation, DPR Construction, CRB Group, AECOM, Fluor Corporation, IPS-Integrated Project Services LLC, Kajima Corporation, Obayashi Corporation, Taisei Corporation, Takenaka Corporation, Shimizu Corporation, Yokogawa Electric Corporation, Mercury Engineering, Mace Group, JGC Holdings Corporation, Turner Construction Company, and M+W Group.
Importance of Cleanroom Expertise in Market Competition
The semiconductor plant construction market is moderately fragmented, with the top 10 firms accounting for 26% of total revenue in 2025. This landscape reflects significant barriers to entry due to stringent facility standards, the complexity of cleanroom construction, advanced engineering requirements, and the critical need for precision in chip manufacturing environments. Leading companies maintain their market positions through diversified engineering and construction services, strong partnerships, global project delivery capabilities, and continuous innovation in cleanroom and plant design. As demand increases for fabs, packaging sites, and high-performance manufacturing infrastructure, these firms are expected to deepen collaborations, drive technological advancements, and expand regionally.
Market Shares of Top Companies in 2025
Leading market participants by revenue share include:
- Exyte GmbH with 9%
- Jacobs Solutions Inc. holding 4%
- Bechtel Corporation at 3%
- Samsung C&T Corporation also 3%
- DPR Construction with 2%
- CRB Group, AECOM, Fluor Corporation, IPS-Integrated Project Services LLC, and Kajima Corporation each at 1%.
Strategies Companies Use to Maintain Competitiveness
To stay competitive, these companies focus on advancing construction technologies that boost efficiency and scalability, designing facilities that enhance cleanroom performance, expanding semiconductor production capacity to improve supply resilience, and integrating smart construction methods that increase automation and precision.
Market Growth from New Builds, Expansions, and Renovations
The combined segments of new construction, facility expansion, and renovation are expected to contribute more than $24 billion in value growth by 2030. Among these, new construction is projected to grow by $16 billion, expansions by $6 billion, and renovations by $2 billion between 2025 and 2030. Key drivers include demand for ultra-clean manufacturing environments, modular building methods for faster fab deployment, investment in resilient utilities and water treatment, modernization of older plants for advanced processes, larger high-purity gas and chemical distribution networks, and automation-ready layouts that facilitate future scaling. These trends reflect an industry-wide push to enhance chip production capacity, operational resilience, and next-generation manufacturing capabilities.
Key Supply Chain and End-User Participants
Raw materials suppliers supporting this market include Saint-Gobain S.A., Linde plc, Air Liquide S.A., Dow Inc., BASF SE, DuPont de Nemours Inc., 3M Company, Shin-Etsu Chemical Co. Ltd., SUMCO Corporation, GlobalWafers Co. Ltd., Siltronic AG, Entegris Inc., Merck KGaA, Versum Materials Inc., Applied Materials Inc., Lam Research Corporation, Tokyo Electron Limited, ASML Holding N.V., KLA Corporation, SCREEN Holdings Co. Ltd., Daikin Industries Ltd., Johnson Controls International plc, Rockwell Automation Inc., Schneider Electric SE, and Mitsubishi Electric Corporation.
Distributors servicing this sector include Arrow Electronics Inc., Avnet Inc., Digi-Key Electronics, Mouser Electronics LLC, Future Electronics Inc., RS Group plc, TTI Inc., Newark Electronics, Allied Electronics & Automation, Farnell Global, WPG Holdings Limited, Macnica Inc., Ingram Micro Inc., Tech Data Corporation, TD SYNNEX Corporation, Synnex Corporation, ScanSource Inc., Bechtle AG, ALSO Holding AG, Esprinet S.p.A., Redington Limited, Westcon Group, Exclusive Networks SA, Mindware FZ LLC, and EET Group A/S.
End users utilizing semiconductor plant construction services encompass major chipmakers such as Taiwan Semiconductor Manufacturing Company Limited, Samsung Electronics Co. Ltd., Intel Corporation, Micron Technology Inc., SK Hynix Inc., Texas Instruments Incorporated, Broadcom Inc., Qualcomm Incorporated, NVIDIA Corporation, Advanced Micro Devices Inc., Infineon Technologies AG, NXP Semiconductors N.V., Renesas Electronics Corporation, STMicroelectronics N.V., Analog Devices Inc., Sony Semiconductor Solutions Corporation, GlobalFoundries Inc., United Microelectronics Corporation, Semiconductor Manufacturing International Corporation, Tower Semiconductor Ltd., Powerchip Semiconductor Manufacturing Corporation, Vanguard International Semiconductor Corporation, Bosch Semiconductor Manufacturing, Wolfspeed Inc., and onsemi.
Our 2026 reports feature deeper market intelligence with market attractiveness scoring and analysis, total addressable market (TAM) analysis, company scoring matrix graphics and tables, Excel-based forecasting dashboards, market hotspots infographics, key technologies and future trend analysis, and updated graphics and tables.
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company.
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
